
Last updated: October 2026
Every fall, the same question shows up in veteran group chats and comment sections: how much is my VA check going up, and when will I actually see it? Search for an answer and you'll find dozens of "2027 pay charts," many of them published before the government announced anything.
The yearly raise follows a predictable pattern, and you don't need to guess or trust a random website to understand it. This post covers the 2027 increase, how it's set, the current pay chart, when the new rates reach your bank account, and how to check the official numbers yourself.
The 2027 Increase
VA disability compensation goes up 3.6% for 2027. That's the cost-of-living adjustment, or COLA, a yearly increase meant to keep benefits in step with inflation. The Social Security Administration (SSA) announced the percentage on October 14, 2026, and you can see it on SSA's COLA page.
For comparison, the 2026 COLA was 2.8%. The final number came in right around what most forecasters expected, which was 3.5% to 3.6%.
How the VA COLA Is Set
VA doesn't come up with its own raise. Each year, Congress passes a law that sets the VA increase, and for decades it has set the VA COLA equal to the Social Security COLA. It isn't automatic: the Veterans' Compensation Cost-of-Living Adjustment Act of 2023, for example, covered only one year. For the December 1, 2026 increase, the bill is S. 4487.
SSA bases its COLA on the CPI-W, the Consumer Price Index for Urban Wage Earners and Clerical Workers. The CPI-W is a government measure of how much prices have risen for a typical working household. Here's how the math works:
SSA averages the CPI-W readings for July, August, and September of the current year.
It compares that average to the same three months from the year before.
The percentage increase between the two becomes the COLA.
Because September's inflation data is part of the formula, the announcement comes in mid-October, right after the Bureau of Labor Statistics releases that month's numbers.
The practical takeaway: you don't have to apply for the raise, and nobody at VA decides whether you deserve it. Once it's set, it applies to everyone receiving disability compensation.
VA Disability Pay Chart by Rating
VA pays based on your combined disability rating, which runs from 0% to 100% in steps of 10%. A 0% rating means VA agrees your condition is service-connected but isn't paying monthly compensation for it right now. Here are the current monthly rates for a veteran with no dependents. They've been in effect since December 1, 2025.
| Combined rating | Monthly rate since Dec. 1, 2025 (veteran alone) |
|---|---|
| 10% | $180.42 |
| 20% | $356.66 |
| 30% | $552.47 |
| 40% | $795.84 |
| 50% | $1,132.90 |
| 60% | $1,435.02 |
| 70% | $1,808.45 |
| 80% | $2,102.15 |
| 90% | $2,362.30 |
| 100% | $3,938.58 |
I'll add the 2027 column once VA publishes its official table on its compensation rates page. VA sets the exact amounts, so a number you calculate yourself by multiplying these rates by the COLA can be off by a few cents.
Dependents add to your payment starting at 30%
If your combined rating is 30% or higher, you get extra pay for dependents. Find your rating on VA's chart, then the row that matches your household. Dependents that can add to your payment include:
A spouse, at 30% and above.
Children: each child under 18 adds an amount, and VA lists separate amounts for children 18 to 23 who are in school.
Dependent parents: one or two parents who depend on you financially.
A spouse who needs Aid and Attendance: extra pay when your spouse needs help from another person with daily activities like bathing, dressing, or eating.
At 10% and 20%, there's one amount, because dependents don't change payments at those levels.
Combined ratings aren't simple addition
The rating you look up is your combined rating, not the total of your individual ratings. VA uses the combined ratings table in 38 CFR 4.25, where each new rating applies only to the part of you that isn't already rated as disabled. The result is rounded to the nearest 10%, with values ending in 5 rounded up. A 30% and a 20% rating, for example, combine to 40%, not 50%. My VA disability calculator walks through how VA combines multiple ratings, step by step.
TDIU follows the 100% row
TDIU stands for Total Disability based on Individual Unemployability. It's for veterans whose service-connected conditions keep them from holding a steady job, even if their combined rating is below 100%. If you have TDIU, you're paid at the 100% rate, so use the 100% row. My TDIU eligibility guide covers who qualifies and how to apply.
When the New Rates Take Effect
The new rates take effect December 1, 2026. But VA pays for each month after it ends, on the first business day of the next month. That means the payment for December, the first one at the new rate, normally arrives January 1.
This year, January 1, 2027 falls on a holiday, so the payment for December arrives early, on Thursday, December 31, 2026. The same thing happened last year: the first payment at the 2026 rate arrived December 31, 2025.
| Step | 2026 cycle | 2027 cycle |
|---|---|---|
| COLA percentage | 2.8% | 3.6% |
| New rates take effect | December 1, 2025 | December 1, 2026 |
| Last payment at the old rate | December 1, 2025 (for November) | December 1, 2026 (for November) |
| First payment at the new rate | December 31, 2025 (for December) | December 31, 2026 (for December) |
If your December 1 deposit looks the same as November's, nothing is wrong. Watch for the December 31 payment instead.
Who Else Gets the Same COLA
The same increase applies to other benefits on the same schedule:
Dependency and Indemnity Compensation (DIC): a tax-free monthly payment for eligible surviving spouses, children, and some parents of veterans or service members. DIC rates rise by the same percentage. My guide to DIC and survivor benefits explains who qualifies.
Veterans Pension: a needs-based benefit for wartime veterans with limited income. Its rates rise by the same percentage. If you're not sure which program you're on, here's the difference between pension and disability compensation.
Social Security: retirement and SSDI benefits rise by the same percentage, since it's the same COLA.
Military retired pay: retired pay uses the same CPI-W formula, so it rises by the same percentage.
Each benefit arrives on its own payment schedule, so the raises may not all show up on the same day.
How to Check the Official Numbers Yourself
You don't need a middleman to find out what you'll be paid. Two official sources cover everything:
SSA's COLA page: where the percentage is announced each October.
VA's compensation rates page: the official dollar amounts for every rating and dependent combination. It updates once the new rates are official.
Be careful with search results. Many of the sites ranking for "2027 VA pay chart" are claims-coaching companies or legal marketing sites. Some publish projected charts with exact dollar amounts, formatted to look final, weeks before the government announces anything. If a chart doesn't come from VA.gov, treat it as an estimate.
If you have questions about your own payment, like whether your dependents are on file or why your amount doesn't match the chart, an accredited Veterans Service Organization (VSO) can help for free. A VSO is a group like the American Legion, VFW, or DAV that has representatives accredited by VA. You can find an accredited representative on VA.gov.
Conclusion
The percentage gets the headlines, but the timing is what matters for your budget. The new rates take effect December 1, and this year your first payment at the new rate arrives December 31.
Your next step: open VA's compensation rates page and confirm the rate you're getting now matches your rating and dependents. Then set a reminder for December 31 to check that your first payment at the new rate came through.
Trying to make sense of your rating or your payments? Ratings math and VA rules can be confusing, even when you've read everything. Schedule a free consultation and we'll walk through it together.
Continue Reading
Everything you need for your claim, in one bundle.
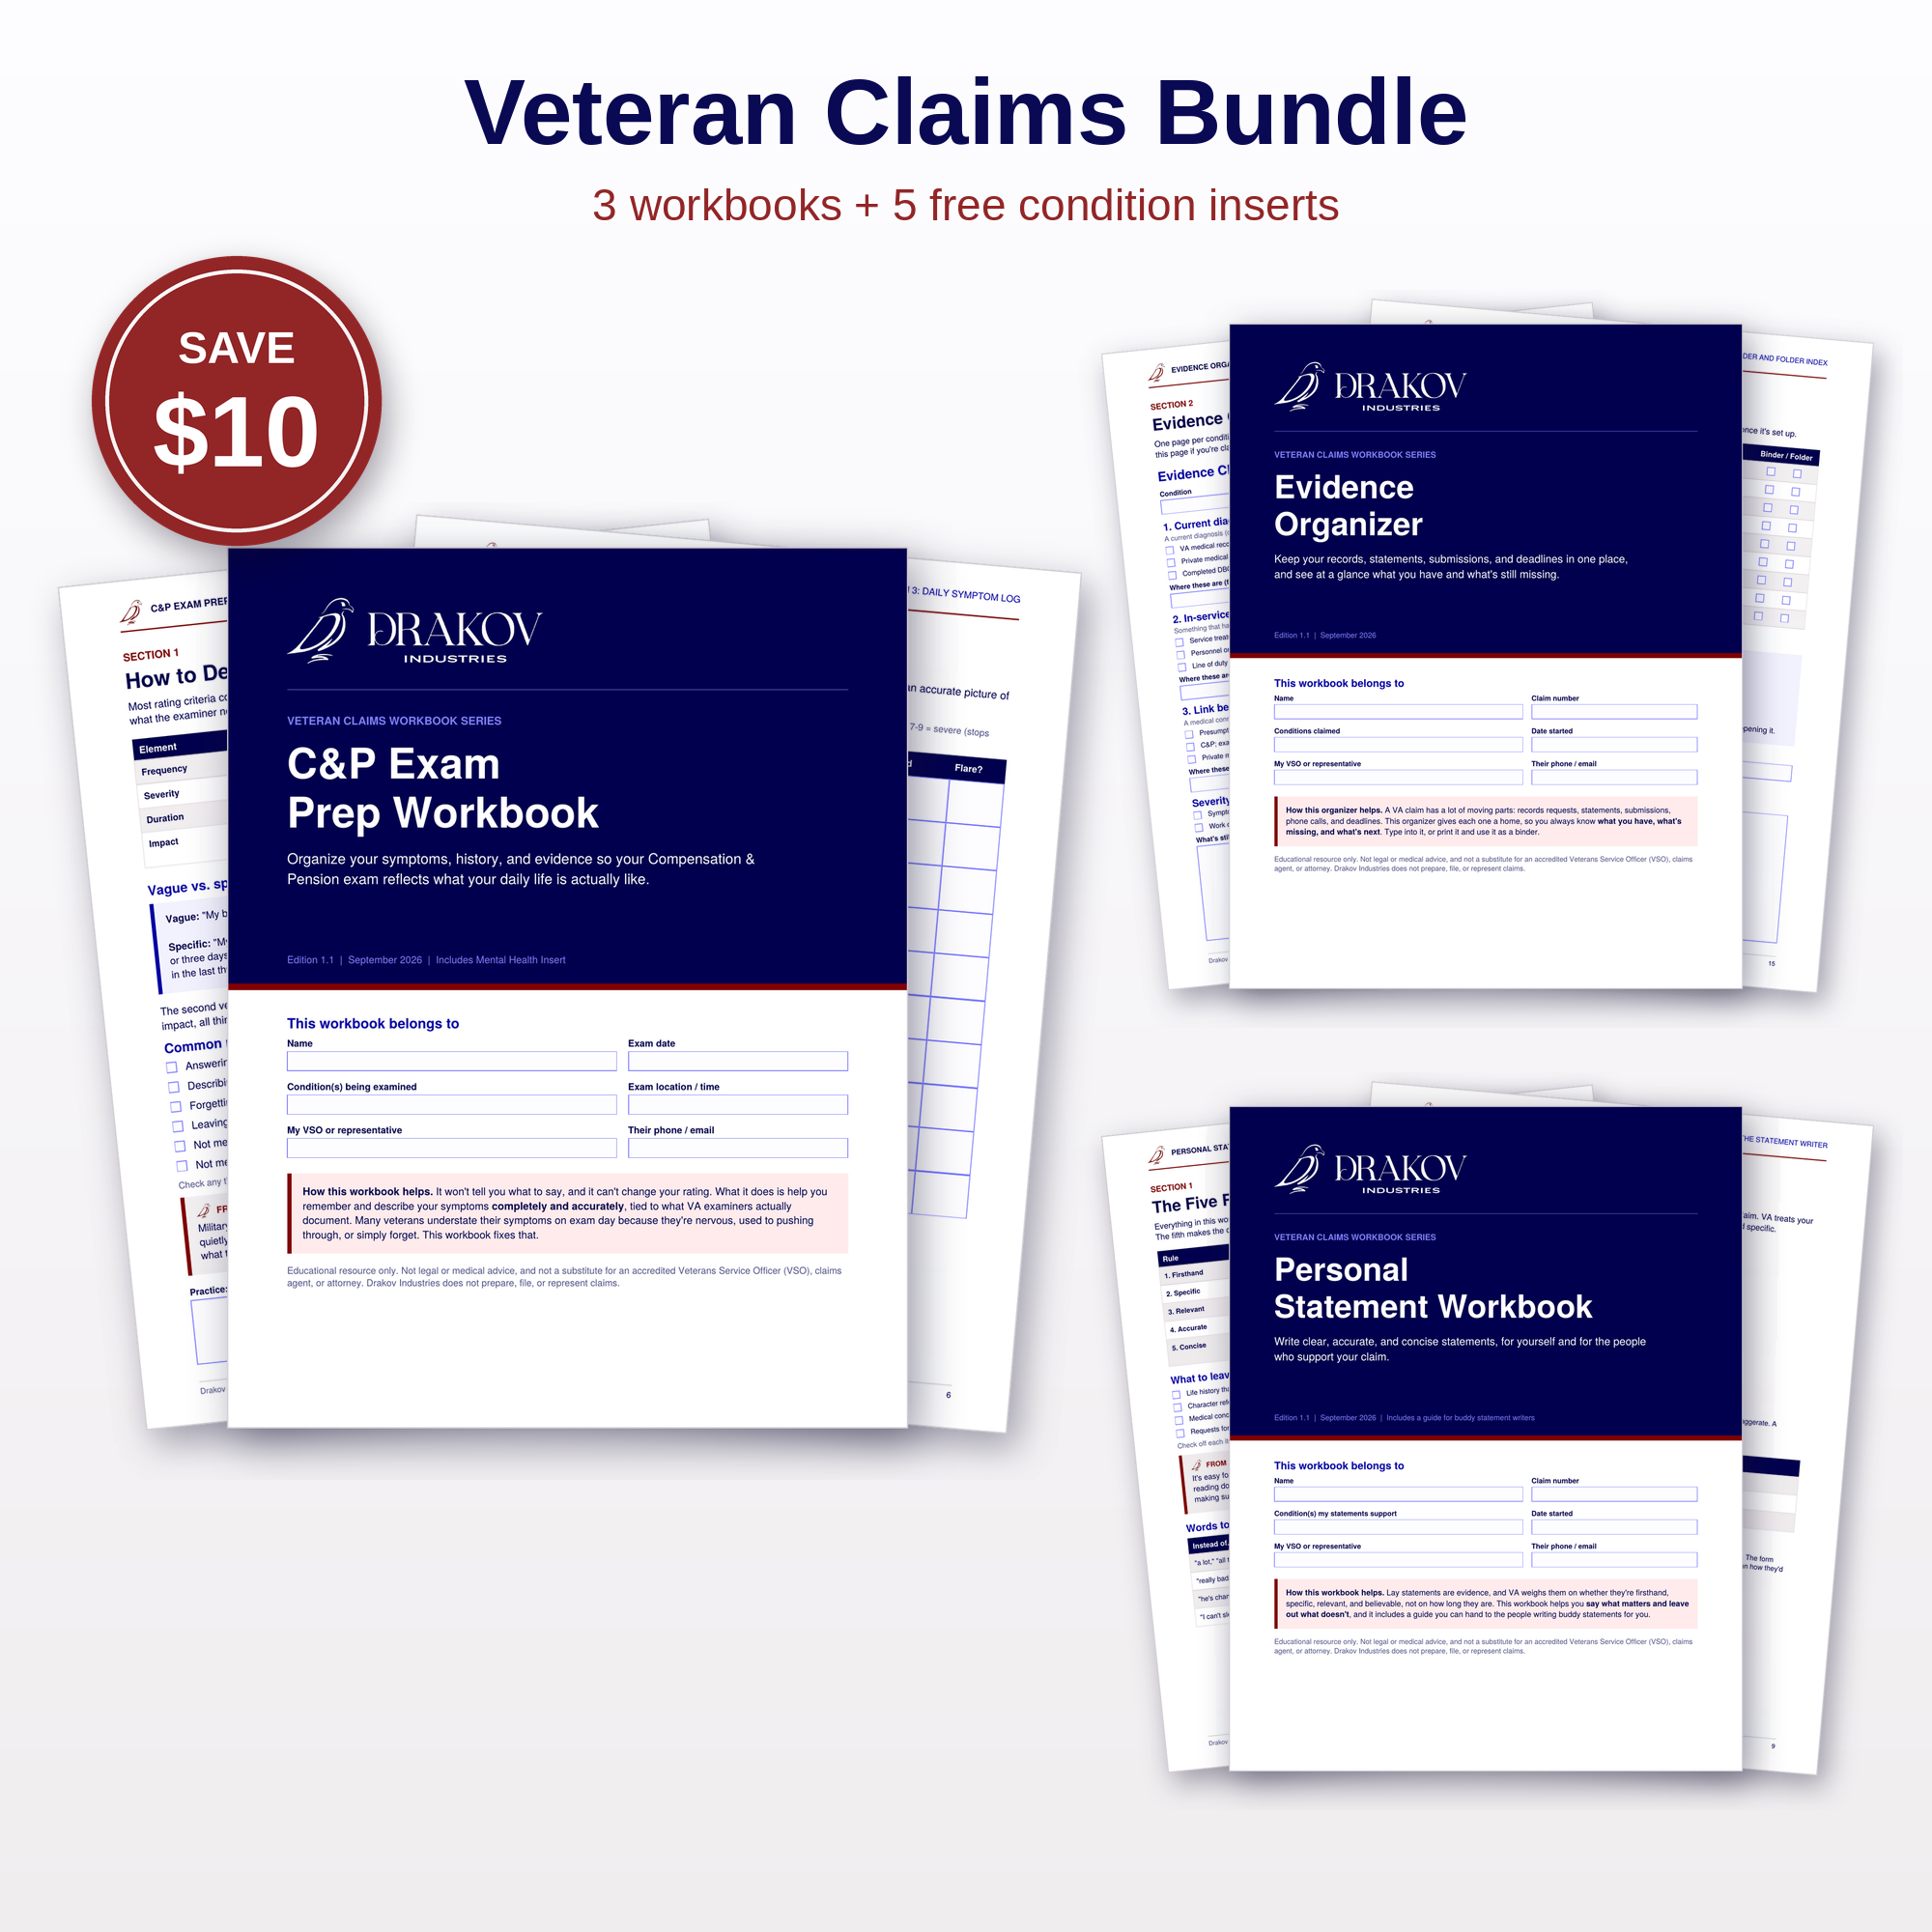
A VA claim has three big moments: gathering your evidence, writing your statements, and walking into your C&P exam. Each workbook in this series was built for one of them. Together, they take you from the day you decide to file to the day you get your decision, and they cost less than buying them separately.
What's inside:
C&P Exam Prep Workbook: a two-week prep plan, a daily symptom log, flare-up and functional impact worksheets, and a one-page exam summary, so you can describe your condition completely and accurately on exam day.
Evidence Organizer: a claim overview with an Intent to File tracker, an evidence checklist for each condition, logs for records requests, submissions, and calls, and a matching binder and folder index, so you always know what you have, what's missing, and what's next.
Personal Statement Workbook: the five rules of a strong statement, a step-by-step guide to writing and editing your own, and a printable guide to hand to the people writing buddy statements for you.
Five free condition inserts: Mental Health, Migraines & Headaches, Tinnitus & Hearing, Sleep Apnea, and Joints & Spine. Use only the ones that apply to you.
Best value: $35 for the complete set, compared with $45 if you buy all three workbooks separately. You save $10.
Three fillable PDFs (47 pages total), plus five condition inserts, delivered as a single download. Type into them or print them.
Everything in these workbooks is based on public VA rules and forms. What you're paying for is the organization, the plain-language guidance, and lessons from someone who's been through it, plus free updates whenever the rules change.
Educational resources only. Not legal or medical advice. Drakov Industries does not prepare, file, or represent claims. For help with your claim, contact a VA-accredited Veterans Service Officer. Their help is free.